Equal Housing Lender
Listed by
Linda Savage
Financing by
John Morgan
EPiQ Lending™
EPiQ Lending™

For Sale

Listed at

$778,000

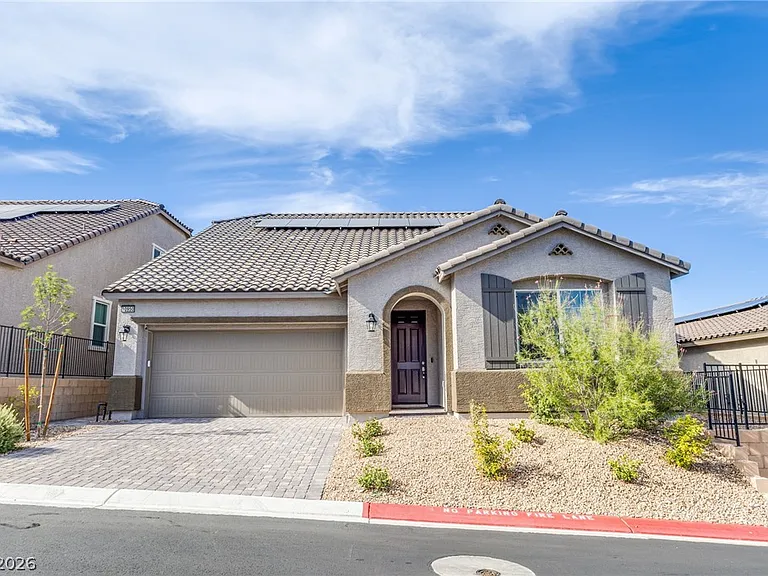
10950 Cilantro Ave, Las Vegas, NV

Estimates based on rates from October 14, 2026

Seller-paid rate reduction

The seller of this home is participating in EPiQ Lending’s™ rate reduction program — contributing $7,780 (1% of the price) to discount your rate and monthly payment when using EPiQ Lending™ to finance this property. The rates below already include it.

VA · 30yr · 0% down

7.750%7.490%

$6,212$6,070/mo

30yr · 0% down · APR 7.729%

Loan $778,000

+ HOA $105/mo

Conventional · 30yr · 5% down

7.490%7.250%

$6,045$5,924/mo

30yr · 5% down · APR 7.515%

Loan $739,100 · MI $363/mo

+ HOA $105/mo

Conventional · 30yr · 25% down

7.375%7.125%

$4,549$4,450/mo

30yr · 25% down · APR 7.430%

Loan $583,500

+ HOA $105/mo

Conventional · 15yr · 25% down

7.000%6.490%

$5,763$5,598/mo

15yr · 25% down · APR 7.152%

Loan $583,500

+ HOA $105/mo

Conventional · 30yr · 25% down · Investment

7.750%7.375%

$4,699$4,549/mo

30yr · 25% down · APR 7.704%

Loan $583,500

+ HOA $105/mo

Jumbo · 30yr · 20% down

7.375%7.125%

$4,817$4,712/mo

30yr · 20% down · APR 7.477%

Loan $622,400

+ HOA $105/mo

Rates shown include the seller’s $7,780 rate-reduction contribution. Payment includes property taxes for this home and estimated HOI. Enter your details for a payment tailored to your credit score and down payment.

Listing agent
Linda Savage
Loan officer
John MorganNMLS# 1785932
EPiQ Lending™
Rates and payments shown are estimates for this property and are not a commitment to lend, a credit decision, or a rate lock. They are based on pricing dated October 14, 2026, change daily, and are not locked until a rate lock is issued. Final terms depend on credit approval, verified income and assets, an appraisal, and underwriting.
These quotes assume a credit score of 800 or better and a 30-day rate lock. A lower credit score, a different down payment, or a different property type will change your rate and payment — enter your details for a quote based on your own credit.
APR is calculated on each option's own loan amount — not on the list price. Each rate below is bought down with discount points, where one point equals 1% of that option's loan amount; the split shows who pays them.
  • VA · 30yr · 0% down — loan $778,000 · APR 7.729% · 2.76 total points: 1.00 seller-paid, 0.75 lender credit, 1.01 paid by you (about $7,850)
  • Conventional · 30yr · 5% down — loan $739,100 · APR 7.515% · 2.52 total points: 1.05 seller-paid, 0.75 lender credit, 0.71 paid by you (about $5,270)
  • Conventional · 30yr · 25% down — loan $583,500 · APR 7.430% · 2.84 total points: 1.33 seller-paid, 0.75 lender credit, 0.76 paid by you (about $4,429)
  • Conventional · 15yr · 25% down — loan $583,500 · APR 7.152% · 3.05 total points: 1.33 seller-paid, 0.75 lender credit, 0.96 paid by you (about $5,625)
  • Conventional · 30yr · 25% down · Investment — loan $583,500 · APR 7.704% · 3.04 total points: 1.33 seller-paid, 0.75 lender credit, 0.95 paid by you (about $5,555)
  • Jumbo · 30yr · 20% down — loan $622,400 · APR 7.477% · 2.82 total points: 1.25 seller-paid, 0.75 lender credit, 0.82 paid by you (about $5,085)
The monthly figure includes principal and interest, this property's actual annual taxes of $3,500, estimated homeowners insurance of $2,723 per year and mortgage insurance where it applies. It does not include HOA dues of $105 per month, shown separately. Taxes and insurance are estimates; your actual escrow will be set at closing.
The seller's $7,780 contribution is applied to buying your rate down and is subject to the purchase contract and to the maximum contribution your loan program allows. If the program limit is lower, the difference may be applied to other closing costs.
VA options require eligible veteran, active-duty, or surviving-spouse status and may include a VA funding fee, which can be financed; exempt borrowers pay none.
Conventional mortgage insurance is estimated from the credit score and down payment shown and may be removed once you reach 20% equity.
Jumbo and high-balance options exceed the standard conforming loan limit for this county and carry their own credit, reserve, and down-payment requirements.
Second-home financing requires at least 10% down and investment-property financing at least 15% down; those programs price differently than a primary residence.
EPiQ Lending™ · John Morgan NMLS# 1785932 · 10750 W Charleston Blvd #180 · Branch NMLS# 1971649